Alert!

Anti-Money Laundering in Banking Sector
Anti Money Laundering
November 3, 2026
February 1, 2024


Anti-money laundering (AML) in banking is the set of laws, controls, and processes banks use to prevent, detect, and report money laundering, terrorist financing, sanctions evasion, and proliferation financing. The core controls it includes are customer due diligence (CDD), screening, transaction monitoring, risk assessment, suspicious activity reporting, and governance.
Regulators in 2026 expect banks to ensure and provide proof that controls are risk-based, data-driven, explainable, tested, and proportionate. Only maintaining documentation is not valid anymore. For example, AMLA, through Article 26 of Regulation (EU) 2024/1624, defines ongoing monitoring as keeping customer information up to date while tracking transactions over time to detect any unusual activity.
Why AML matters for banks
Banks are the initial entry point to any financial system, and criminals attack and test them first. Weak controls are costly. In October 2026, the U.S. Department of the Treasury and federal regulators fined Bank of America $1.21 billion over major anti-money laundering and sanctions control failures. Global regulations are improving and trying to make it harder for financial criminals, but the latest data show that risk fluctuates worldwide. The Basel AML Index 2025 scored 177 jurisdictions and scales them on a scale of 1 to 10. It reports that the global anti-money laundering risk average sat at 5.28 out of 10. While 54% of countries tightened their financial security this past year, 43% actually became more vulnerable to financial crime.
How money laundering moves through a bank
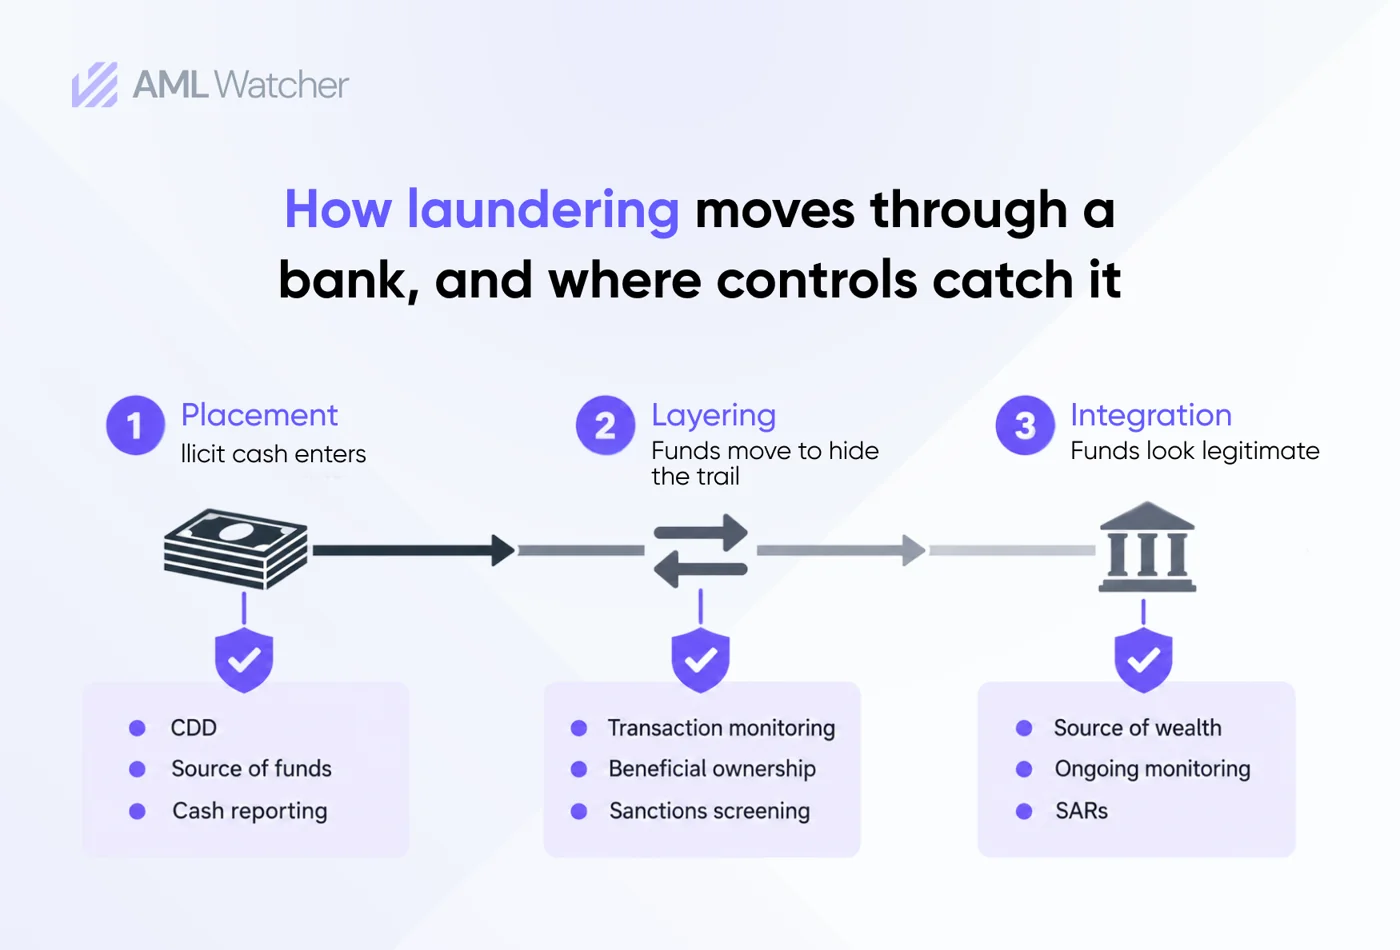
| Stage | Consequences | Control that Should Catch it |
| Placement | Illegal cash enters the system, often through small quantities | CDD, source of funds checks, cash reporting |
| Layering | Funds move through transfers, most commonly through shell companies and jurisdictions to hide the trail | Transaction monitoring, beneficial-ownership checks, sanctions screening |
| Integration | Funds reappear as legitimate wealth, such as property or business investment | Source-of-wealth review, ongoing monitoring, regular suspicious activity reports |
The AML process in banking, step by step
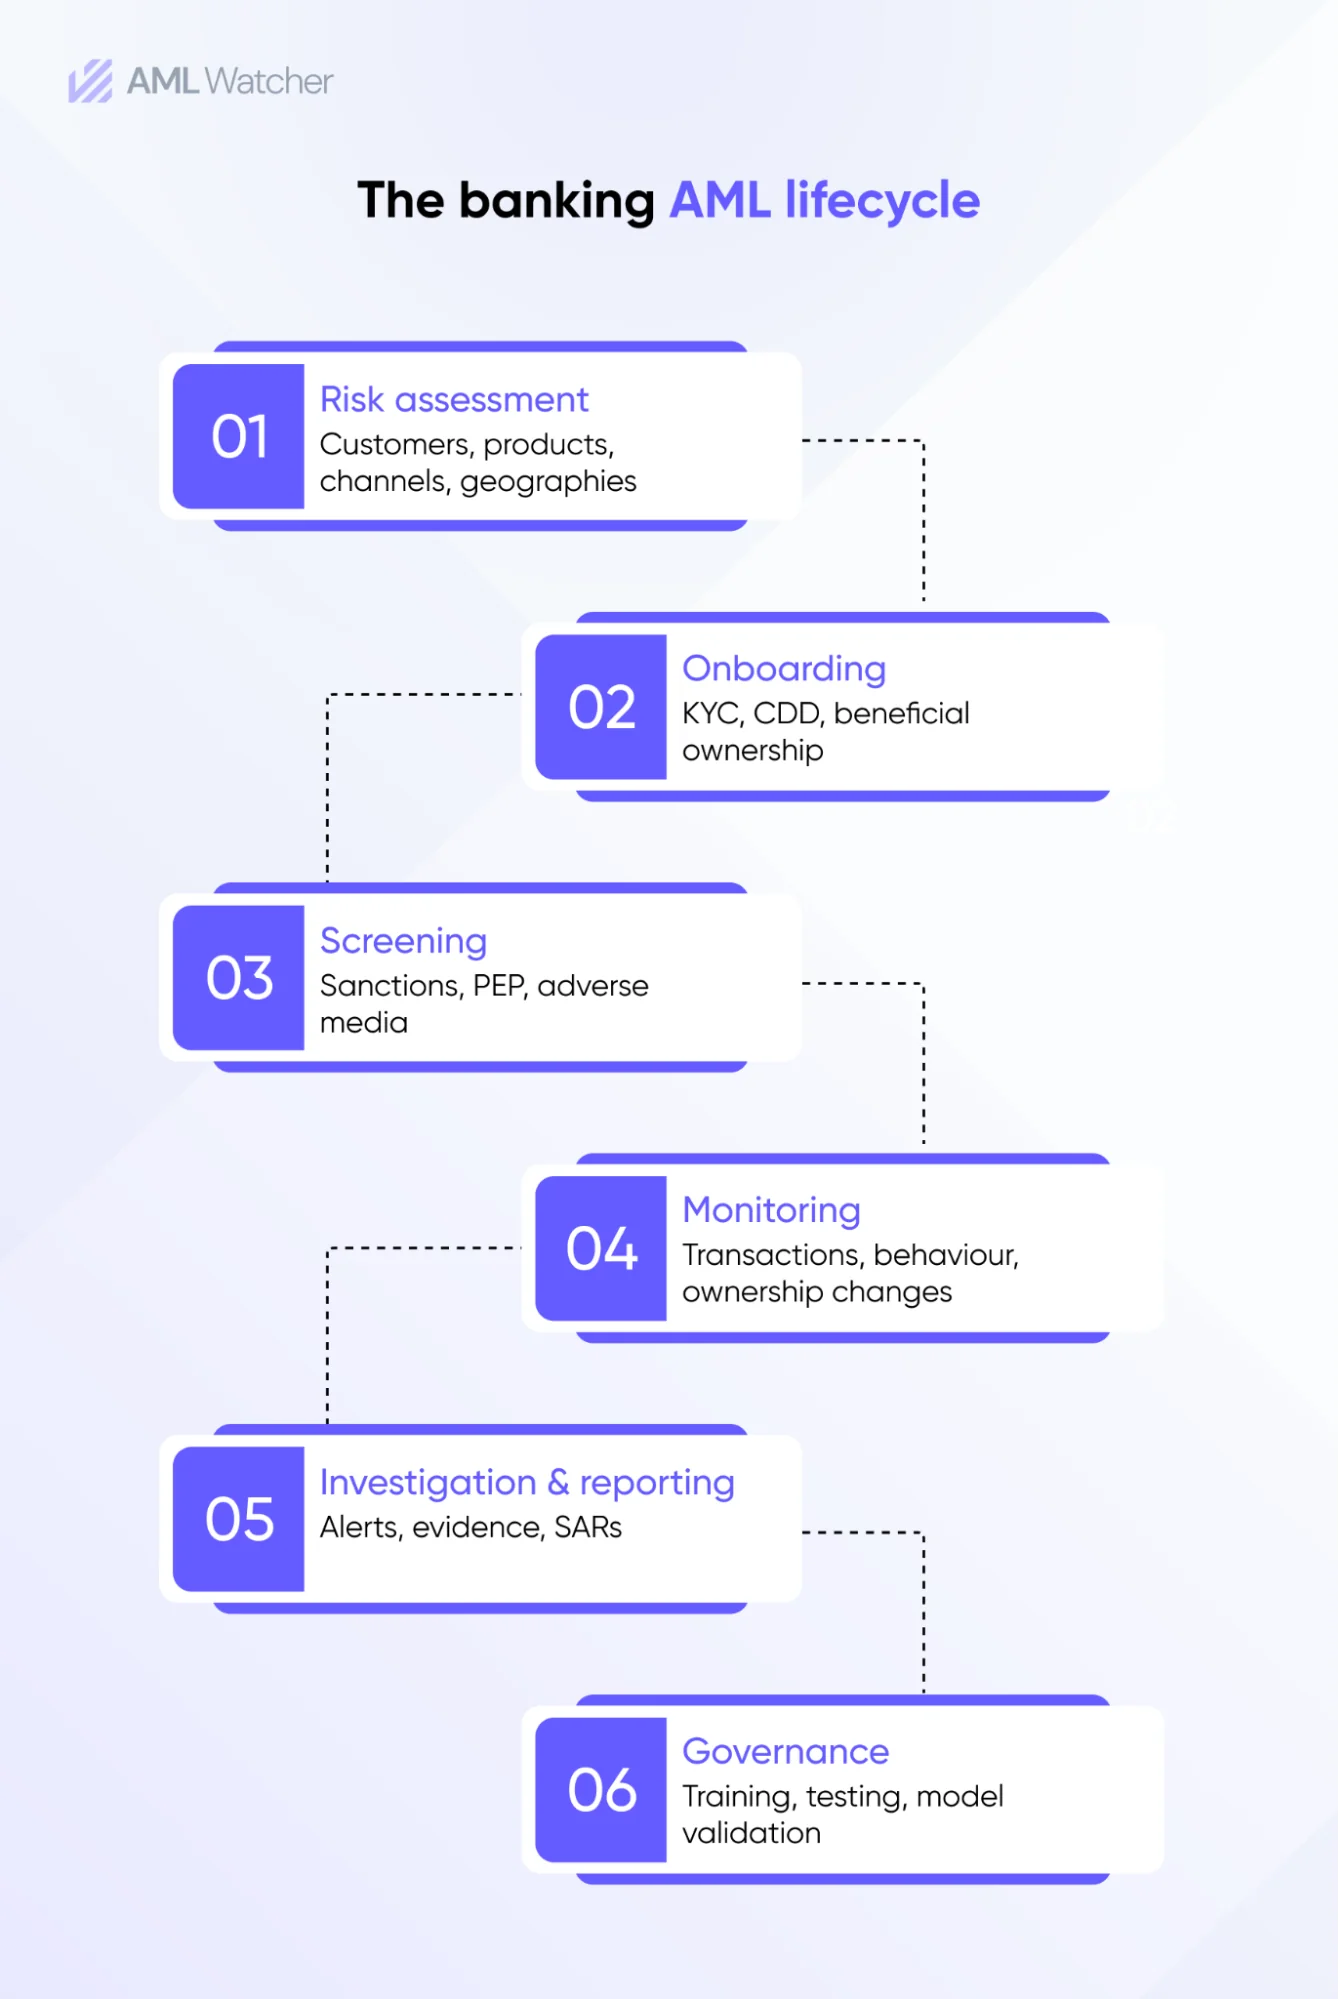
Effective Aml in banking sector is carried out in the following 6 steps:
- Risk is assessed across customers, products, channels, and geographies by conducting an enterprise-wide risk assessment.
- During the onboarding process, Identity must be verified through beneficial owners and the purpose of the relationship.
- Screening of customers, owners, and counterparties against sanctions, PEP, watchlist, and adverse-media data is done.
- Transactions Monitoring and keeping customer information up to date.
- Investigating alerts, documenting decisions, and filing suspicious activity reports.
- Testing and improving by providing training to staff, testing independently, and recalibrating controls.
Core AML controls in banks
Customer due diligence and beneficial ownership
CDD is the foundation and among the core components of aml for banks. Banks identify and verify customers and beneficial owners, connect the relationship, build a risk profile, and then apply enhanced due diligence (EDD) to the customers that are identified as higher-risk customers. FATF Recommendation 12 calls for senior-management approval and source-of-wealth checks for politically exposed persons (PEPs); these stringent measures apply automatically to foreign PEPs, whereas for domestic PEPs and international organisation leaders, they are required only when a higher risk is identified.
Sanctions, PEP, and adverse-media screening
Screening checks customers, owners, and counterparties against sanctions lists, PEP data, and negative news. A match is treated as a risk signal, not proof of wrongdoing or a declared conviction. Analysts verify identifiers, assess source reliability, and record the decision. Adverse media screening follows the same principle.
Transaction and ongoing monitoring
Ongoing monitoring and transaction monitoring compare the activity with the customer’s expected profile. Common red flags that must not be ignored are:
- Repeated deposits just below reporting thresholds
- Rapid in-and-out flows of funds
- Activity inconsistent with the customer’s profile or designated business
- Complex ownership structure with no clear commercial rationale
- Unexpected high-risk jurisdictions or counterparties
Reporting and recordkeeping
Banks report suspicious activity to the national financial intelligence unit (FIU) under the local law of any country. FinCEN in the US requires a suspicious activity report (SAR) generally within 30 days of detection, and a currency transaction report (CTR) for cash transactions above $10,000. Case files should show the evidence reviewed, including the rationale for escalation or closure, and who approved it. The Bank Secrecy Act is the foundation of these US requirements.
Governance
Strong internal governance plays an important role in an effective compliance system. The FATF in its Recommendation 18 states that financial institutions must ensure and establish internal controls, including a designated AML officer, active board oversight, refresher employee training, and independent audit testing to ensure operational accountability. Executive leadership should make sure these governance mechanisms support mitigating risk rather than institutional avoidance. FATF guidelines expressly prohibit sweeping de-risking and the mass termination of customer categories. Good governance comes down to how top management runs a bank’s risk strategy. Instead of taking the easy way out and closing all accounts in a certain industry or country, board members and executives need to build a system that looks at customers one by one.
An Overview of Banking AML Regulations
| Region | Core Framework | Authorities |
| Global | FATF Recommendations: Recommendation 10 CDD, Recommendation 12 PEPs, Recommendation 20 suspicious transaction reporting | FATF |
| United States | Bank Secrecy Act of 1970, Money Laundering Control Act of 1986 | FinCEN, OCC, Federal Reserve, OFAC for sanctions |
| European Union | AML Regulation (EU) 2024/1624, applying from 10 July 2027 | AMLA, national supervisors, FIUs |
| United Kingdom | Money Laundering Regulations 2017 | FCA, UK FIU |
For local requirements, see our AML country guides.
What changes in 2026
2026 saw a lot of changes worldwide by regulatory authorities to make their AML compliance programs effective.
United States’ FinCEN proposed a new rule on April 7 2026 that focuses on program excellence and effectiveness rather than just measuring technical gaps, and it will take effect 12 months after publication following the June 9 comment deadline.
European Union’s Authority for Anti-Money Laundering and Countering the Financing of Terrorism (AMLA) published draft ongoing monitoring guidelines on 3 June 2026. They cover periodic and event-driven updates to customer information, and how monitoring systems are designed, tested, and must be executed. The consultation process is closed on 3 September, and final guidelines are expected in Q4 2026. Banks that are using AI or advanced analytics should now be ready for closer scrutiny of governance and explainability.
The requirement is quite clear that banks must show what data they used, why an alert fired, what evidence supported the decision, and how the control was tested.
Why AML programs fail
| Failure | Impact | Fix |
| Poor Data Quality | Incomplete ownership and customer records | Validate data at onboarding; keep one customer view |
| Static Rule | New typologies are missed | Tune and validate models on a schedule |
| Alert Overload | Real risk buried in false positives | Prioritise by risk; document thresholds |
| Fragmented Systems | Screening, monitoring, and case data stay disconnected | Integrate workflows with a full audit trail |
| Blanket derisking | Exclusion replaces risk management | Apply proportionate EDD |
| Overdependence on AI | Judgment is replaced, not supported | Keep human review for high-risk decisions |
Key takeaways
- AML in banking prevents, detects, and reports illicit-finance risk.
- Core controls include CDD, screening, monitoring, risk assessment, reporting, governance.
- Instead of closing entire groups of accounts to avoid risk, banks should apply a risk-based approach by applying standard checks to low-risk customers and deeper scrutiny to high-risk ones based on their individual threat levels.
- FinCEN proposal and AMLA draft show that 2026 is about effectiveness and explainability.
- Technology helps only when factors like data quality and human supervision are strong.
How AML Watcher Can Help You Stay Compliant?
AML Watcher, with its fully automated screening tools, helps you to meet evolving tech and regulatory requirements. We at AML Watcher offer a comprehensive AML solution for banks that includes crypto wallet & vessel screening, sanctions & watchlist screening, theInternational Leaks Database, and PEP & adverse media monitoring. From Fintech to Gambling, Crypto to the Legal sector, we secure the world’s most sensitive financial operations. Book yourFREE DEMO and overcome the compliance challenges that might be costing your business.
Frequently Asked Questions
AML in banking includes the laws, controls, and processes banks use to prevent, detect, and report money laundering and terrorist financing.
AML process in banking is the set of methods that banks use to measure risk during the onboarding process of customers, using methods like KYC and CDD, screening against sanctions, PEP, and adverse-media data, monitoring transactions, investigating alerts, filing suspicious activity reports, and testing and improving existing controls.
No. KYC is a part of AML and is the process of identifying and verifying customers. AML is a broader term, and it also covers risk assessment, screening, monitoring, reporting, training, and governance.
It depends on the jurisdiction and the local laws. US requires SARs to be reported within 30 days of detection. Banks in the EU and UK report to their national FIU under local deadlines.
- No commitment needed
- Complete AML Database at your service
- Access our all-in-one dashboard


Tier-2 PSPs in ... must demonstrate automated monitoring, layered CDD, &...
See the Full Regulatory Expectation70–80% less manual work, 95% less fatigue, TruRisk Agent makes compliance effortless.
Experience Agentic AMLMove Beyond Articles. Activate AML Intelligence.
Switch to AML Watcher today and reduce your current AML cost by 50% - no questions asked.
- Find right product and pricing for your business
- Get your current solution provider audit & minimise your changeover risk
- Gain expert insights with quick response time to your queries