

 Alert!

3 Stages of Money Laundering Explained: Placement, Layering, and Integration
Money Laundering
Aug, 18 2026
April 26, 2024


Money laundering is a process through which criminals attempt to conceal the origins of illicit proceeds and make those funds appear legitimate. Although laundering schemes vary considerably, the process is commonly explained through three stages: placement, layering, and integration.
Understanding these stages helps financial institutions and other regulated businesses recognize how illicit funds can enter the financial system, become harder to trace, and eventually re-enter the legitimate economy.
The three-stage model provides a useful framework for understanding money laundering, but real-world schemes do not always follow these stages in a fixed sequence. Criminals may combine stages, repeat particular activities, or use legitimate businesses and financial structures from the outset. Therefore, compliance teams should view placement, layering, and integration as indicators of how illicit proceeds can move through the financial system rather than as a mandatory sequence.
The Three Stages of Money Laundering are:
Below are the stages of the money laundering cycle that must be identified to effectively detect financial crimes that undermine the stability of global economic systems.
Placement
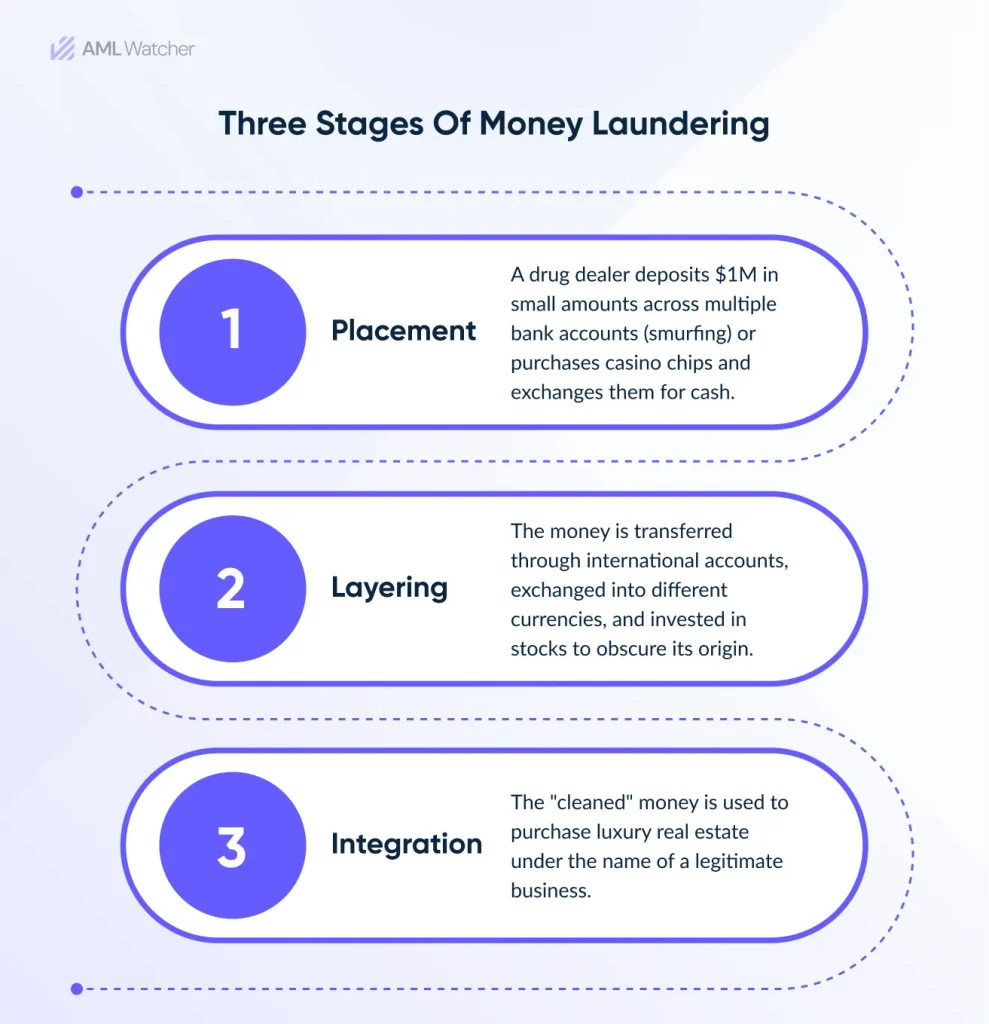
Placement is the stage in which illicit proceeds are first introduced into the legitimate financial system. The objective is to move criminal proceeds away from their original source while reducing the likelihood of detection.
Illicit proceeds can originate from crimes such as drug trafficking, fraud, corruption, human trafficking, and organized crime. Placement attempts to move those proceeds into financial accounts, businesses, or other assets where their criminal origin becomes harder to establish.
Criminals may use techniques such as structuring or “smurfing,” in which funds are divided into smaller transactions or distributed across multiple accounts. Money mules may also be used to receive or transfer illicit funds on behalf of others. These activities can make it more difficult for financial institutions to identify the original source of funds.
Common placement indicators include:
- Unusual cash deposits that do not align with a customer’s expected activity
- Multiple transactions structured to avoid reporting or monitoring thresholds
- Third-party deposits without a clear economic purpose
- Sudden increases in cash activity
- Funds entering an account that are inconsistent with the customer’s known source of funds
Layering
Layering involves moving illicit proceeds through a series of transactions, accounts, entities, or jurisdictions to make the source and ownership of the funds more difficult to trace. The activity can involve domestic or international transfers, changes in asset ownership, business transactions, or other financial arrangements.
Layering can involve multiple intermediaries, corporate structures, professional services, and financial institutions. This can create fragmented transaction trails that make it harder for compliance teams to establish the source and ultimate destination of funds.
Money mule networks can also support layering by moving funds through accounts controlled by individuals who transfer or receive money on behalf of criminals. CIFAS data has highlighted the scale of money-mule activity in the UK, including the recruitment of younger individuals via social media.
Layered transactions may pass through corporate entities, accounts in different jurisdictions, or structures with opaque beneficial ownership. Where ownership information is difficult to establish or customer due diligence is weak, criminals may find it easier to conceal the individuals who ultimately control or benefit from funds.
Trade-based money laundering can also be used to disguise the movement of illicit proceeds through international trade. Criminals may manipulate invoices, prices, quantities, or descriptions of goods and services to transfer value while creating the appearance of legitimate commercial activity.
Common layering indicators include:
- Rapid transfers between unrelated accounts
- Transactions involving multiple jurisdictions without a clear business rationale
- Complex ownership or corporate structures
- Payments that do not align with the customer’s stated business activity
- Repeated movement of funds through intermediary accounts
- Trade transactions with unusual pricing, quantities, or counterparties
Integration
Integration is the stage in which illicit proceeds are presented as legitimate wealth, income, investments, or business proceeds. Criminals may use assets such as real estate, businesses, securities, or high-value goods to give illicit funds an appearance of legitimate economic origin.
Certain sectors may be more exposed to laundering due to characteristics such as cash intensity, complex ownership structures, subjective asset valuations, or high-value transactions. Real estate, construction, art markets, and other asset-intensive sectors can therefore require appropriate risk-based controls.
Requirements vary by jurisdiction, but the broader objective is to identify and mitigate the risk that financial systems and businesses are used to move or conceal illicit proceeds.
Global AML Regulations and Enforcement
A collective effort to stem criminal activities and facilitate acts of money laundering was initiated when drug and human trafficking overtook the streets of the United States and Europe. UNODC (Global AML Regulations and Enforcement) estimated that around $800 billion of generated money is laundered each year, which presents the only detected stats while millions of dollars go undetected.
The modern world has seen and heard a lot about rigorous enforcement actions by governing bodies, which have established the term Anti-Money Laundering (AML) measures. These global AML laws are designed to implement strict screening and verification protocols to detect and prevent money laundering across 3 stages and associated predicate crimes.
AML frameworks have developed over decades through national legislation and international standards. The U.S. Bank Secrecy Act, enacted in 1970, established important reporting and recordkeeping requirements, while the Financial Action Task Force, established in 1989, developed international standards for combating money laundering and related financial crime. FATF later expanded its standards to address terrorist financing and other forms of illicit finance.
Enforcement actions demonstrate that AML failures can expose institutions to financial penalties, regulatory restrictions, remediation requirements, and reputational damage. These outcomes also show why AML programs need controls proportionate to the risks posed by customers, products, services, and jurisdictions.
Recent enforcement actions provide practical examples of how weaknesses in customer due diligence, transaction monitoring, beneficial ownership controls, and suspicious activity reporting can expose financial institutions to money laundering risk.
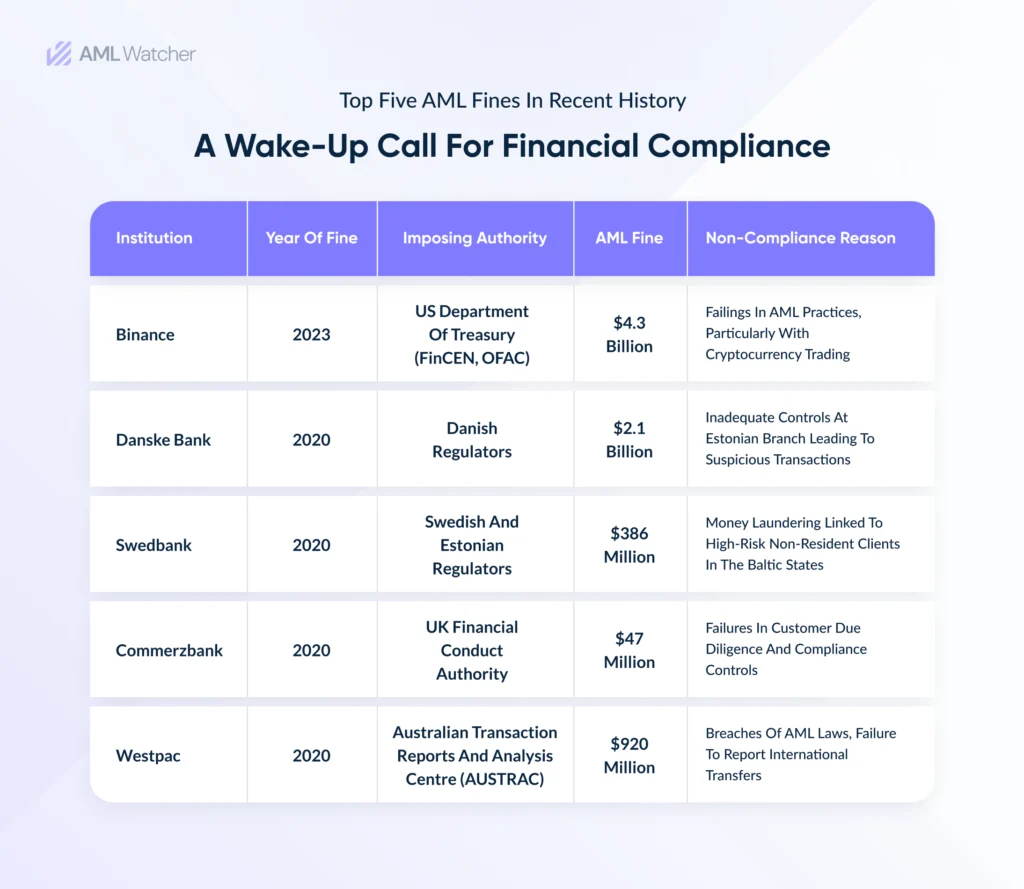
Four Sectors Exposed to Money Laundering Risk
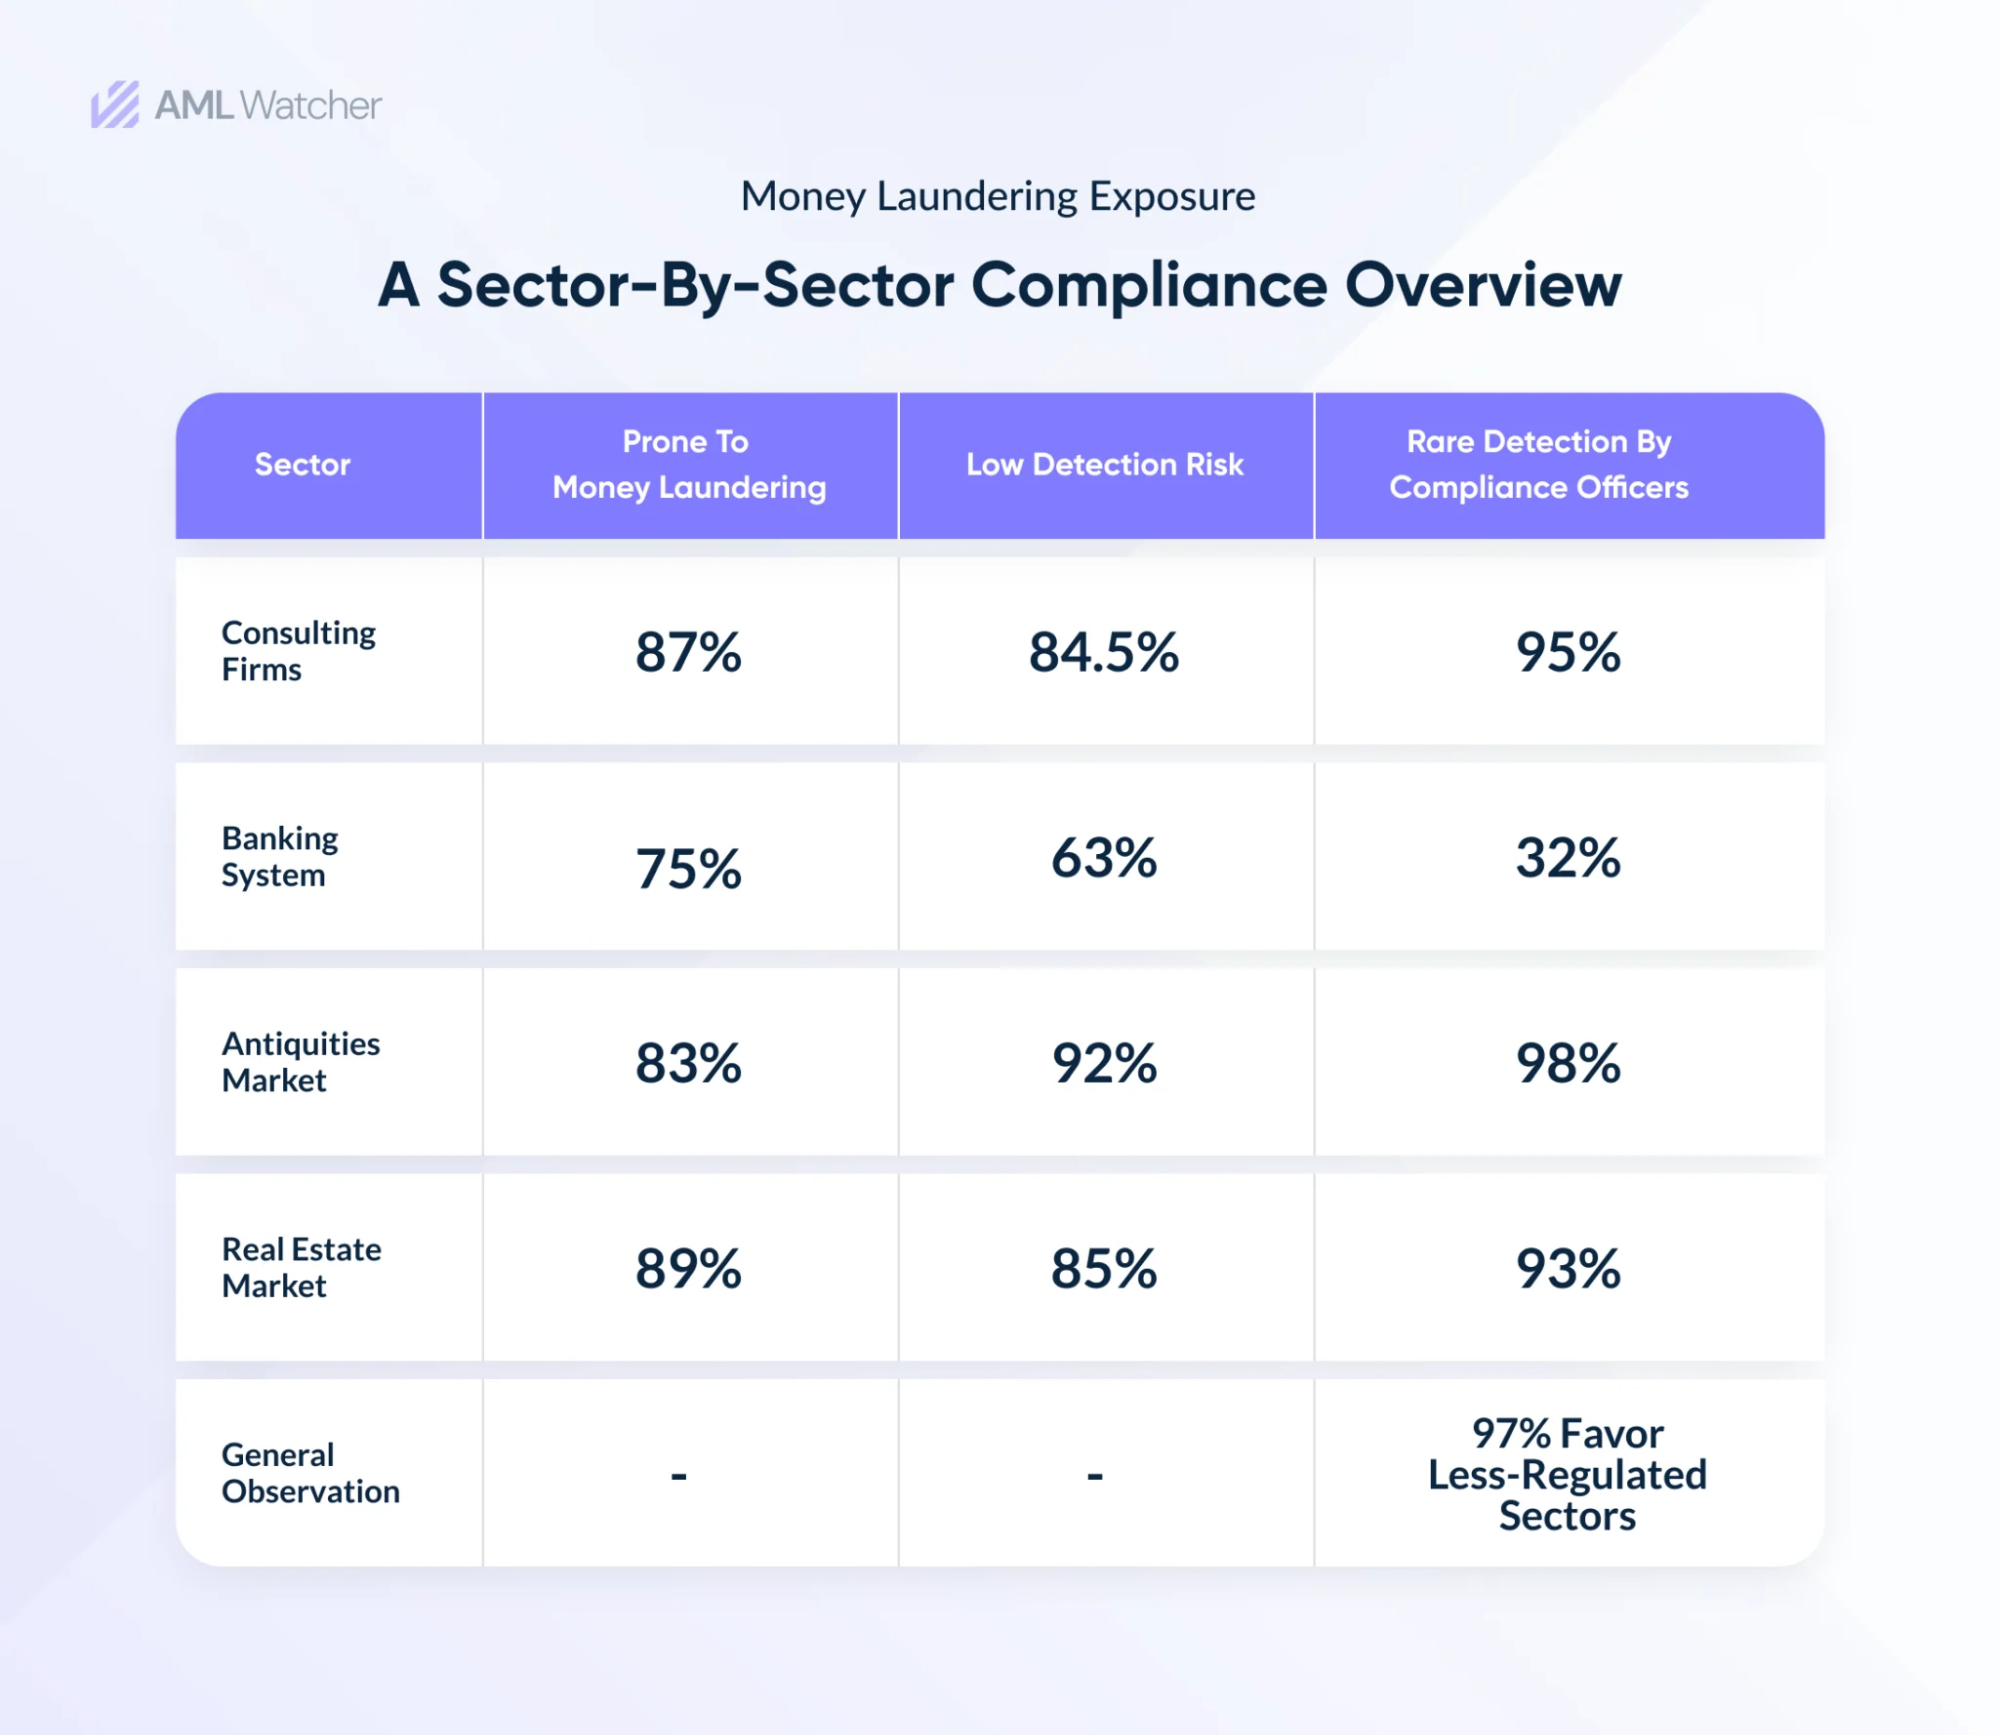
Money laundering schemes can exploit sectors where transactions involve cash, complex ownership structures, high-value assets, international activity, or subjective valuations. Understanding these characteristics can help compliance teams assess where laundering risks may arise.
Money Laundering Through Banks
Banks remain an important point of exposure because they process deposits, transfers, payments, and other financial activity. Strong customer due diligence and beneficial ownership controls can help institutions understand who is using an account and the purpose of the relationship.
Complex corporate structures, offshore arrangements, and opaque beneficial ownership can make it difficult to establish who ultimately controls an account or benefits from transactions.
Money Laundering Through Consulting Firms
Professional and consulting services can present AML risks when complex corporate structures, opaque ownership arrangements, or transactions with unclear economic purposes are involved. The risk depends on the nature of the service, the customer profile, the jurisdiction, and the applicable regulatory requirements.
Money Laundering Through Antiquities
The subjective valuation of certain art and antiquities can create opportunities for criminals to move or store value in assets that may be difficult to price consistently. The prices of such materials depend on the buyer’s preferences or interest in the art pieces, making it difficult to estimate the actual cost of a material.
Money Laundering Through Real Estate
Real estate can be exposed to money laundering risk because transactions may involve high-value assets, complex ownership structures, intermediaries, and substantial financing arrangements. Property purchases, renovations, rental income, and subsequent sales can potentially be used to disguise the origin of illicit funds.
These renovated buildings are rented out for extended periods, while the illegal proceeds are mixed with rental income, turning black money into clean money. In the final stages, the property is sold at elevated prices, marking a market price increase, and the laundered money eventually enters legitimate financial systems.
Below is the quantitative analysis of the sectors discussed above regarding the likelihood of money laundering, supported by the research study.
How Can Businesses Strengthen Their AML Compliance?
It is inevitable that institutions will follow regulatory guidelines and help law enforcement agencies fight money laundering. AML compliance programs typically combine several controls, including customer due diligence, beneficial ownership checks, sanctions and watchlist screening, transaction monitoring, suspicious activity reporting, ongoing customer monitoring, employee training, and independent testing.
Compliance Culture & Awareness
Effective AML compliance depends not only on technology and procedures but also on a strong compliance culture. Staff involved in onboarding, payments, customer service, operations, and compliance should understand the organization’s AML policies, escalation procedures, and reporting responsibilities. To create a credible and accountable compliance culture within the system, institutions need to raise staff awareness of the importance of these measures.
Know Your Customer & AML Checks
AML requirements vary by jurisdiction and business type, but regulated firms generally need risk-based customer due diligence that supports customer identification, verification, understanding of the customer relationship, and ongoing monitoring.
KYC, AML screening, and transaction monitoring address different parts of the risk picture. KYC helps establish who the customer is and understand the relationship. Screening can identify relevant sanctions, PEP, watchlist, or adverse media risks. Transaction monitoring examines financial behavior for patterns that may warrant further investigation.
How AML Watcher Supports AML Risk Screening
Money laundering risks can emerge from customer identities, sanctions exposure, politically exposed persons, adverse media, and other risk signals. AML Watcher supports compliance teams with screening capabilities designed to help identify relevant risk information during customer and ongoing compliance processes.
Request a Demo to explore how AML Watcher can support the organization’s AML requirements.
Frequently Asked Questions
The 4 stages of money laundering are:
- Placement: Introducing illicit funds into the financial system, such as depositing cash into a bank account.
- Layering: Masking the actual ownership of funds through complicated, organized transactions such as transferring the funds between multiple accounts
- Integration: Mixing the dirty money with clean money to make it legitimate funds, such as investing in business and then using it for further purposes like funding terrorism
- Concealment: Additional steps are used to hide the origin of the money, further preventing detection of funds, such as through offshore accounts.
Common warning signs include unusual cash deposits, rapid movement of funds between unrelated accounts, transactions involving high-risk jurisdictions, complex ownership structures, unexplained third-party payments, and activity that does not match a customer’s known profile or business purpose.
Financial institutions can detect potential money laundering through risk-based customer due diligence, beneficial ownership checks, sanctions and watchlist screening, transaction monitoring, ongoing customer monitoring, and suspicious activity reporting. These controls help identify unusual patterns and assess whether financial activity requires further investigation.
Transaction monitoring helps financial institutions identify unusual patterns that may indicate attempts to move, conceal, or integrate illicit proceeds. Monitoring can highlight rapid transfers, unusual transaction volumes, activity across multiple jurisdictions, and transactions that differ from a customer’s expected behavior.
- No commitment needed
- Complete AML Database at your service
- Access our all-in-one dashboard


Tier-2 PSPs in ... must demonstrate automated monitoring, layered CDD, &...
See the Full Regulatory Expectation70–80% less manual work, 95% less fatigue, TruRisk Agent makes compliance effortless.
Experience Agentic AMLMove Beyond Articles. Activate AML Intelligence.
Switch to AML Watcher today and reduce your current AML cost by 50% - no questions asked.
- Find right product and pricing for your business
- Get your current solution provider audit & minimise your changeover risk
- Gain expert insights with quick response time to your queries